Market Pulse
Where Laclede County stands — September 2026
What's Available
Feature breakdown of active parcels — based on listing descriptions
Land Value Metrics
Improved parcels vs. raw ground — asking prices vs. 12-month closed sales
With Structures
Land Only
| Acreage | 🏚 Improved | 🌲 Unimproved |
|---|---|---|
| 5–10 ac | — | $10,194 5 parcels |
| 10–20 ac | $98,187 ⚠ 1 | $12,482 9 parcels |
| 20–50 ac | $19,115 5 parcels | $7,498 10 parcels |
| 50–100 ac | $10,313 3 parcels | $15,000 ⚠ 1 |
| 100+ ac | $3,319 ⚠ 1 | — |
| Acreage | 🏚 Improved | 🌲 Unimproved |
|---|---|---|
| 5–10 ac | $16,429 3 parcels | $7,825 18 parcels |
| 10–20 ac | $42,759 3 parcels | $10,828 10 parcels |
| 20–50 ac | $12,000 8 parcels | $6,000 13 parcels |
| 50–100 ac | $5,000 11 parcels | $3,750 3 parcels |
| 100+ ac | $4,526 6 parcels | — |
⚠ Low Data = fewer than 3 parcels in band. Median may not be statistically representative.
Inventory Distribution
Where is active supply concentrated right now?
What This Means For You
This is a buyer's market, and the numbers back it up — 7 months of supply, median sold price down nearly a quarter from last month to $240,000, and sellers accepting 92.9% of list price on average. With 35 active parcels and water access on 43% of them, there's real selection if you're after Niangua River or creek frontage without paying premium rates. Take your time on due diligence; days on market are still running over four months, so there's no need to rush an offer on road access or boundary questions.
Pricing discipline matters more than ever this period — median $/acre held at $7,400, but sold prices dropped sharply and list-to-sale ratio slipped to 92.9%, signaling buyers are negotiating harder. If your land has river or creek frontage, hunting habitat, or usable timber, lead with that in your listing — it's what's pulling offers in a market with 7 months of supply sitting against you. Price it realistically from day one rather than testing the market high; with inventory already thinning from last month, well-positioned parcels are still moving, but overpriced ones will sit.
Month-Over-Month
September 2026 vs. prior month — Land & Farm
| Metric | September 2026 | August 2026 | Change |
|---|---|---|---|
| Median Sold Price | $240,000 | $317,000 | ▼ 24.3% |
| Median List Price | $319,900 | $189,900 | ▲ 68.5% |
| Median $/Acre (Sold) | $7,400/ac | — | — |
| Avg Days on Market | 123 days | 150 days | ▲ Faster by 27 days |
| Active Parcels | 35 | 41 | ▼ 6 |
| Parcels Sold | 5 | 2 | ▲ 3 |
| Months of Supply | 7.00 mo. | 20.50 mo. | ▲ Tightening |
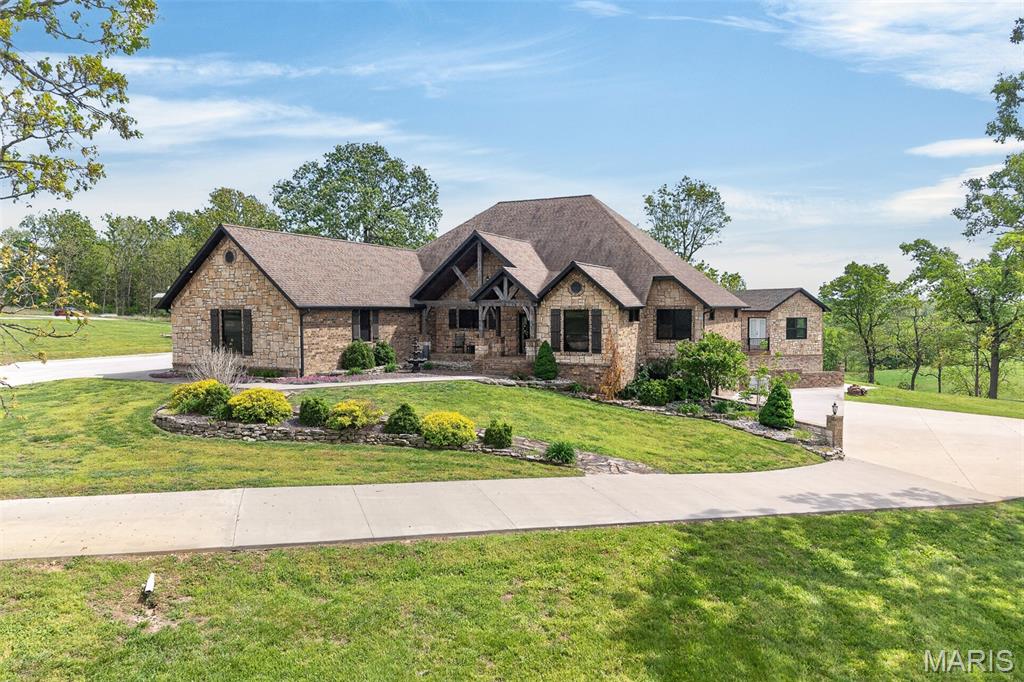
Featured Parcels
Selected active land & farm listings in Laclede County


Activity by Area
Active parcel distribution across communities in Laclede County
| Area | Active | Land / Farm | Median Ask | Median Acres |
|---|---|---|---|---|
| Lebanon | 24 | 18 L / 6 F | $364K | 19.9 ac |
| Richland | 3 | 3 F | $599K | 72.6 ac |
| Stoutland | 3 | 3 L | $170K | 40.0 ac |
| Falcon | 2 | 1 L / 1 F | $277K | 62.0 ac |
| Phillipsburg | 2 | 2 L | $197K | 9.0 ac |
Market Commentary

Our team knows this market — the creeks, the timber, the hunting ground, and the farm soil. Whether you're buying your first tract or selling the family farm, we're here to guide you.
# Laclede County Rural Land & Farm Market Report — September 2026 Laclede County land favors buyers right now, and the numbers back it up plainly. Thirty-five active parcels against five closed sales puts us at seven months of supply — that's a buyer's market by any measure, and sellers who priced aggressively this summer are feeling it. Median sold price came in at $240,000, down almost a quarter from August, while the list-to-sale ratio slipped to 92.9%. Translation: asking price and closing price are diverging more than they were a month ago, and buyers who come in with a firm, researched number are getting sellers to move. If you're selling raw acreage or a hunting tract this fall, price it like you mean to sell it — the data shows this market is punishing optimism. The $/acre gap tells the same story from a different angle. Active listings are asking a median $10,313 per acre, but what's actually closing is running $7,400 per acre — a meaningful spread that smart buyers are using as leverage in negotiations. Average days on market dropped 27 days to 122.6, which sounds like good news for sellers, but combined with the falling sale price and ratio, it more likely reflects the softer-priced properties moving first while overpriced ground sits. Archery season is opening and firearms deer season isn't far behind, which historically pulls serious hunter-buyers off the sidelines — if you've got a tract with timber cover or river bottom that's been lingering, this is the stretch where it finally gets looked at hard. Inventory character this month leans heavily recreational — 43% of active listings touch creek, river, or pond frontage, and with the Niangua River system running through the county, that water access remains the single strongest driver of buyer interest and stronger offers. Nearly half the active listings (49%) include a cabin or retreat structure, and 40% have a barn, shop, or outbuilding, meaning there's real functional value sitting on a lot of this ground beyond bare dirt. Lebanon continues to carry the bulk of activity with 24 active parcels at a median ask of $364,350 on just under 20 acres, while Richland's farm-heavy inventory commands the county's highest asking prices on properties averaging over 70 acres. For buyers hunting pasture or tillable ground, Stoutland and Phillipsburg offer the most affordable entry points in the county — worth a look before hay cutting wraps up and sellers start thinking about next year's lease income instead of a sale.